What Is a Stock Record? Contents, Types and Why It Matters
What is a stock record? It's the per-item log of what you hold, how it has moved, and what it's worth. Here's what a good stock record contains, the main types (perpetual vs periodic, the stock record card, bin card and stock ledger) and where most fall short of the shelf.
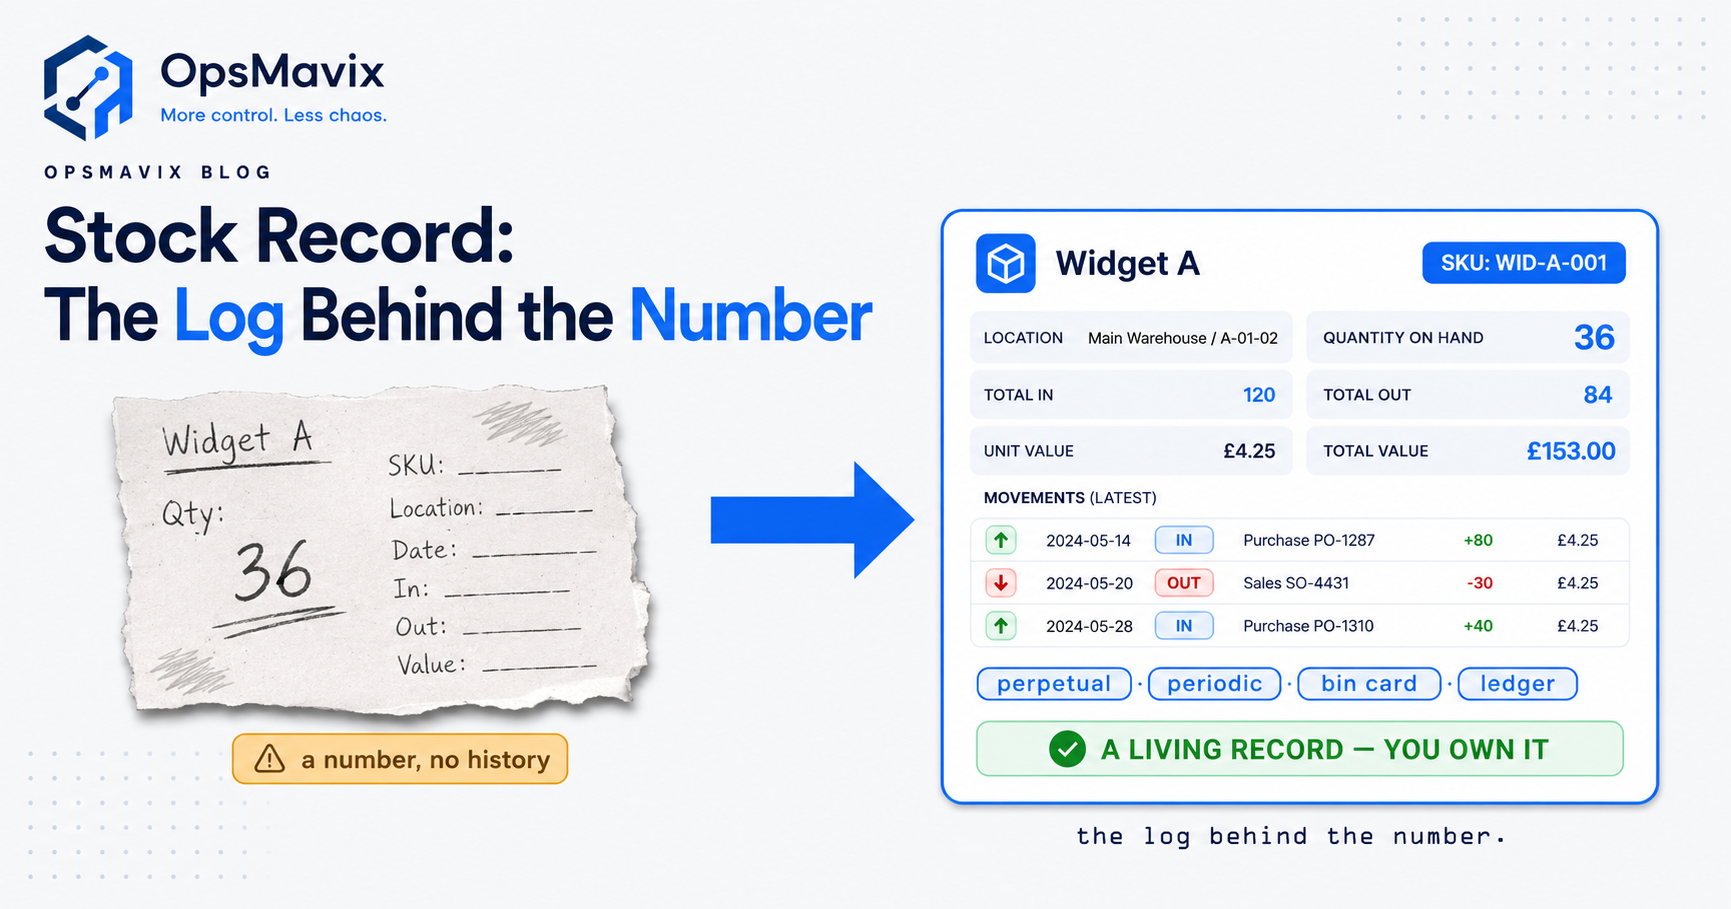
What is a stock record? It’s the per-item log of what you hold, how it has moved, and what it’s worth: one running account for one line of stock. For a given SKU it carries the opening balance, every receipt in and issue out since, and the quantity and value that leaves behind. Not a monthly total, not a figure on the accounts, but a live, item-level history of one thing you keep on a shelf.
The word covers both the individual record for one item and the collection of them that makes up your stock control. This post stays on the concept: what a stock record is, what a good one contains, and the main types (perpetual against periodic, the bin card, the stock ledger) so you can place your own and see where it falls short. The reason accurate records matter at all (cash, customers, decisions) is the layer underneath, covered in the importance of keeping stock control records; here we define the thing itself.
Key Takeaways
- A stock record is the per-item log of what you hold, how it has moved, and what it’s worth — opening balance, movements in and out, closing quantity and value, for one SKU.
- A good record carries five things: what the item is, where it lives, how many there are, every movement that changed the count, and what the balance is worth.
- The types split two ways. Perpetual vs periodic is when the record updates (continuously, or only at a count); the bin card and stock ledger are where it lives (at the shelf, or in the books).
- The movement history is what separates a record from a number. A balance with no in/out trail tells you how many, but never how you got there or who to ask when it’s wrong.
- A stock record is only useful if it matches the shelf. Accuracy, not existence, is what makes it worth keeping — a confidently wrong record is worse than an obviously missing one.
- A spreadsheet stock record is genuinely fine for a small, single-location catalogue. It breaks when movements go untracked, counts go stale, and several people touch stock at once.
What a Stock Record Actually Is
A stock record is the running account for one item of stock. Pick a SKU — a product, a component, a raw material — and the record is everything true about your holding of it: how many you started with, every unit in or out since, and the balance and value it leaves. Its job is to let anyone answer “how many do we have, and what’s it worth” without walking to the shelf.
That idea scales from one card to a full system. A single stock record covers one item; your stock records, plural, are the set across everything you hold — together, the stock control the business runs on. At forty lines you could almost hold it in your head; at four hundred across two sites the record becomes the only version of the truth there is. And it’s not a stocktake: a stocktake is a physical count at a moment, while the stock record is the continuous account that count checks against.
What a Good Stock Record Contains
Strip a stock record to its parts and five things have to be there. Miss one and it can still show a number, but it stops being able to prove it.
What the item is. The identity — a SKU or product code, a description, unit of measure, batch or lot if you track them. Without a clean identifier you get the quiet killer of stock records: two slightly different names for the same thing, and a balance split across both that ties to neither. For barcoded products, the GS1 Global Trade Item Number exists for exactly this job: a company can use it “to uniquely identify all of its trade items” (GS1).
Where it lives. The location — warehouse, zone, bin, or shelf. Trivial for a single room, essential across sites, because “we have twelve” is useless if nobody knows which of three buildings they’re in. It’s what turns a record into something a picker can act on.
How many there are. The quantity on hand — the balance after every movement. Good records separate on hand from available: twelve on the shelf but eight committed to open orders means four are genuinely free to sell, and confusing the two is how overselling starts.
Every movement that changed the count. The part weak records skip, and the most valuable. Each receipt in, each issue out, each transfer and adjustment — logged with a date and, ideally, who did it and why. The movement history is what lets you explain a balance rather than just state it.
What the balance is worth. The value — quantity times unit cost, on a consistent basis. This is where the record meets the accounts: how much cash is sitting on your shelves, and the number an auditor ties back to. For UK tax, HMRC accepts stock valued at “the lower of cost or net realisable value” or on a mark to market basis (HMRC BIM33115), and a UK company that deals in goods must keep “statements of stock held by the company at the end of each financial year” in its accounting records (Companies Act 2006, s386).
The Types of Stock Records
“Types of stock records” gets used two ways, answering different questions. One axis is when the record updates. The other is where it physically lives.
Perpetual vs periodic — when it updates. A perpetual record updates continuously: every movement changes the balance the moment it happens, so it’s live at all times. A periodic record doesn’t — it’s set at a physical count and left, the true figure only re-established at the next count. OpenStax’s accounting textbook calls the perpetual approach “recording as you go”, against a periodic system that updates “at certain, scheduled times at the end of an operating cycle” (OpenStax, Principles of Accounting). Most operations sit between: meant to be perpetual but drifting between counts, which is exactly the gap a rolling cycle count exists to close.
The bin card — the record at the shelf. The item-level record kept at the stock itself: a card (or its digital equivalent) on the bin, showing receipts, issues and running balance for that one location. Its virtue is proximity — updated by the person handling the stock, at the moment they handle it, which is the closest a manual record gets to staying honest.
The stock ledger or stock card — the record in the books. The accounting-side record: the same movements, but valued, kept centrally rather than at the shelf. Where the bin card cares about how many are here, the ledger cares about how many we own and what they’re worth, everywhere. In a manual setup the two are separate documents that have to agree; in a digital one they’re two views of a single record, which removes the reconciliation entirely.
What Is a Stock Record Card?
A stock record card is the stock record for one item, kept on a card or its on-screen equivalent: one card per SKU, with a header that identifies the item and ruled columns that log every receipt, every issue and the running balance. What it is called depends on where it is kept. At the shelf, showing quantities, it is the bin card described above. In the stores office or the accounts, usually with values added, it is the stock card or stock ledger, which a stores department may call a store record card. Guidance in the World Health Organization’s laboratory quality toolkit sums up its job: a stock card “is the basic record needed to establish accurate quantities of individual items to reorder”, and “a separate stock card is needed for each inventory item” (WHO).
The header holds the fixed facts: item name, unit of issue, item code, location, the minimum level that triggers a reorder and the maximum the shelf should hold. Below it is the running log. Each line records the date, the document that caused the movement (a goods received note, a sales order, an adjustment), the quantity in or out, and the balance left behind. Cards kept by the accounts side add unit cost and balance value. Invest Northern Ireland’s business advice service lists similar details for each card: description, value, location, reorder levels, supplier details and past stock history (nibusinessinfo.co.uk).
Here is a worked example for one line of stock:
Item: M8 hex bolts, zinc plated · Unit: box of 100 · Item code: FAS-M8-100 · Location: Aisle 3, bin B-04 · Min: 80 · Max: 400
| Date | Reference | Received | Issued | Balance (boxes) | Unit cost | Balance value |
|---|---|---|---|---|---|---|
| 1 Mar | Opening balance | 120 | £4.20 | £504.00 | ||
| 3 Mar | GRN 1182 | 200 | 320 | £4.20 | £1,344.00 | |
| 5 Mar | SO 4471 | 85 | 235 | £4.20 | £987.00 | |
| 9 Mar | SO 4490 | 60 | 175 | £4.20 | £735.00 | |
| 12 Mar | ADJ 017 (damaged) | 4 | 171 | £4.20 | £718.20 | |
| 16 Mar | Cycle count: 171 counted | 171 | £4.20 | £718.20 |
Read down the card and it answers the three questions a stock record exists for: how many (171 boxes), what they are worth (£718.20), and how the balance got there (one receipt, two sales orders and a write-off for damage). The 16 March count agrees with the card, which shows the record still matches the shelf. If the unit cost changes between deliveries, the card also needs a costing rule; IAS 2 allows first-in, first-out or weighted average cost for items that are ordinarily interchangeable (IFRS Foundation, IAS 2).
Examples of stock records
The card is one example. The others you will meet in most businesses:
- Stock record card or bin card: one item, kept at the shelf or in the stores office.
- Stock ledger: the valued, central record the accounts rely on.
- Goods received note: the document behind every “received” line (see what a goods received note is).
- Goods issued note or picking list: the document behind every “issued” line (see what a goods issued note is).
- Count sheet: the physical count the record is checked against.
- The item screen in inventory software: the digital card, where the movement history is the list of transactions behind the balance.
Types of store records
In a stores department the same paperwork falls into three practical groups:
- Records that hold the balance: stock record cards, bin cards and the stores ledger.
- Records that move it: goods received notes, requisitions, issue notes, returns and transfer notes.
- Records that check it: count sheets and inventory control forms.
The same WHO document describes that last group: an inventory control form lets a store “summarize the quantities and value of stock on hand” and “record discrepancies between the amount of stock that is actually on hand and the amount that should be on hand” (WHO).
Why the Accuracy of the Record Is the Real Test
Here’s the part that decides whether a stock record helps you at all: it has to match the shelf. A record is only as useful as it is true, and one that’s quietly wrong is worse than none — people act on it as if it were right. A missing record makes someone go and check; a confidently wrong one makes them commit stock, quote a job, or skip a reorder on a figure that isn’t real. Auditors test exactly this. Where stock is material, ISA (UK) 501 has the auditor attend the physical count and check that the final inventory records “accurately reflect actual inventory count results” (FRC, ISA (UK) 501).
So “do you keep stock records” is the wrong question and “can you trust the ones you keep” is the right one. Everyone has records of some sort; a spreadsheet counts. The whole game is whether the number in the record and the number on the shelf are the same — and the full case for why that matters, across cash, customers and every buying decision, is laid out in the importance of keeping stock control records. For the definition, it’s enough to say accuracy isn’t a nice-to-have on top of a stock record. It is the record — accuracy, not existence, is the whole measure.
Manual vs Digital Stock Records
A stock record doesn’t care what it’s written on. The mechanics — item, location, quantity, movements, value — are identical whether it’s a card on a bin, a spreadsheet, or a database. What differs is how the record gets updated, and that’s what decides whether it stays true.
A manual record updates because a person remembers to write on it. That works while the record sits next to the stock and the same person handles both — the bin card’s strength. It fails the moment the update moves away from the movement: stock pulled in a hurry and logged later, a receipt booked at day’s end, a transfer nobody wrote down. Every gap between movement and entry is a chance for record and shelf to part.
A digital record can close that gap by making the update a by-product of the work rather than a separate task. Scan an item out to an order and the balance moves itself; the operator isn’t maintaining a record, they’re doing their job. That’s the real point of a barcode inventory system — not the barcode, but that the count changes at the moment and place the stock moves, so there’s no later entry to forget. Memory is where records drift; a by-product update is how they stop.
Where Stock Records Go Wrong
Stock records fail in a few predictable ways, all versions of the same thing: record and shelf stopped agreeing, and nobody noticed until it cost something.
Untracked movements. Something moved and the record didn’t. A sale that didn’t decrement, a return that went back on the shelf but not the count, a breakage nobody logged, a transfer recorded on one side only. Each is a small permanent gap between record and reality, and they accumulate — a shop that logs receipts diligently but forgets breakages reads high forever, drifting further every week.
Stale counts. The record was right once and hasn’t been checked since. A periodic record is stale by design between counts; even a perpetual one goes stale wherever an untracked movement crept in, because nothing catches the error until a count meets it. This is why the record and a physical count have to touch regularly rather than at year-end — the longer the gap, the larger and older the surprise. A rolling cycle count keeps that gap small.
Confidently wrong balances. The worst failure, because it looks like success. The record shows a clean figure, everyone trusts it, and it’s false — phantom stock on the system but not the shelf, or the reverse. When record and reality have fully parted ways and neither you nor the system can say why, you’re in the territory covered in why the stock never matches the system.
One operator described the end state exactly: “we stopped believing the numbers, so everyone just went and counted before they promised anything.” At that point the record has stopped being a record and become a rumour people verify by hand.
When a Spreadsheet Stock Record Stops Being Enough
Be honest about the small case first: for a modest, single-location catalogue, a spreadsheet stock record is genuinely fine. A few dozen lines, one person who touches the stock, movements typed the same day — that record stays accurate indefinitely, and anyone insisting you need software to track forty items is selling you something.
It stops being enough at recognisable pressure points, not a magic number. When more than one person moves stock, so the record depends on several people remembering to type. When the count has to hold across locations or channels at once. When volume climbs past the point where same-day entry survives a busy floor. When on-hand and available diverge because open orders now matter. Cross a few of these and the spreadsheet isn’t a stock record any more — it’s a form people fill in late, always a movement behind the shelf: approximating your stock, not recording it.
The tell is behavioural: people start re-counting before they trust it. The fix isn’t a bigger spreadsheet or a full ERP — it’s a right-sized system where the record updates as the stock moves, so the number in the system is the number on the shelf without anyone maintaining it by hand. That’s the design intent behind an inventory system: not more features, but a stock record that stays true because it’s a by-product of the work rather than a chore.
FAQ
What is a stock record in simple terms?
It’s the running log for one item of stock — what it is, where it’s kept, how many you have, every movement in and out, and what the balance is worth. Its job is to let anyone answer “how many do we have and what’s it worth” without checking the shelf. Your full set of these records, across everything you hold, is your stock control.
What should a stock record contain?
Five things: the item’s identity (SKU, description, unit of measure), its location, the quantity on hand, a history of every movement that changed that quantity (receipts, issues, transfers, adjustments — dated), and the value of the balance. The movement history is the part weak records skip and the most useful to keep, because it lets you explain a balance rather than just state it.
What are the main types of stock records?
Two axes. By when they update: perpetual records change continuously with every movement; periodic records are set at a physical count and left until the next one. By where they live: a bin card is the item-level record kept at the shelf, updated by whoever handles the stock; a stock ledger is the valued, central record kept in the books. In a digital system the two become one record, not separate documents.
Is a spreadsheet a good enough stock record?
For a small, single-location catalogue with one person handling stock, yes — it can stay accurate indefinitely. It stops being enough when several people move stock, when the count has to hold across locations or channels, or when volume makes same-day entry unrealistic. The failure isn’t the spreadsheet; it’s that the update depends on someone remembering, which breaks the moment the floor gets busy.
How OpsMavix Can Help
Knowing what a stock record is and what a good one contains is the easy half. The hard half is keeping it true once real work runs over it — which is where OpsMavix builds. We put the stock record inside the system people already use to receive, pick and ship, so every movement updates the balance as a by-product of the job: one shared figure for on hand and available, a full movement history behind it, a value that ties to the books without a separate reconciliation. Shaped to how your stock moves, so people enter data instead of working around it.
If your team has started counting the shelf before they’ll trust the system, your stock records have stopped doing their one job — and every promise made on a figure nobody believes is a risk carried blind. Book a free Operations Leak Audit.
Sources
- World Health Organization, Laboratory Quality Stepwise Implementation tool, Annex A3: Examples of inventory control forms (stock or bin card): https://extranet.who.int/lqsi/sites/default/files/attachedfiles/Guidance_on_specifications_for_TB_lab_supply_AA3.pdf
- nibusinessinfo.co.uk (Invest Northern Ireland), Stock control systems: keeping track manually: https://www.nibusinessinfo.co.uk/content/stock-control-systems-keeping-track-manually
- IFRS Foundation, IAS 2 Inventories: https://www.ifrs.org/issued-standards/list-of-standards/ias-2-inventories/
- GS1, Global Trade Item Number (GTIN): https://www.gs1.org/standards/id-keys/gtin
- HMRC, Business Income Manual BIM33115, Stock: valuation: the valuation bases: https://www.gov.uk/hmrc-internal-manuals/business-income-manual/bim33115
- legislation.gov.uk, Companies Act 2006, section 386: https://www.legislation.gov.uk/ukpga/2006/46/section/386
- OpenStax, Principles of Accounting, Volume 1, 6.2 Compare and Contrast Perpetual versus Periodic Inventory Systems: https://openstax.org/books/principles-financial-accounting/pages/6-2-compare-and-contrast-perpetual-versus-periodic-inventory-systems
- Financial Reporting Council, ISA (UK) 501 (Updated September 2025): https://media.frc.org.uk/documents/ISA_UK_501_Updated_September_2025.pdf